
Smart Utilities Market Positioned For Sustained Growth At 13.1% CAGR Through 2030
Smart Utilities Market
Smart Utilities Market Outlook

Smart Utilities Market
The Business Research Company’s Smart Utilities Global Market Report 2026 – Market Size, Trends, And Forecast 2026-2035
LONDON, GREATER LONDON, UNITED KINGDOM, October 28, 2026 /EINPresswire.com/ -- The smart utilities sector is rapidly evolving as energy providers and technology companies work together to modernize utility infrastructure. With growing investments in digital systems and advanced metering, this market is set to transform how electricity and water services are managed, monitored, and optimized worldwide. Let’s explore the current market outlook, key growth drivers, leading players, and emerging trends shaping the future of smart utilities.
Smart Utilities Market Size and Regional Leadership by 2030
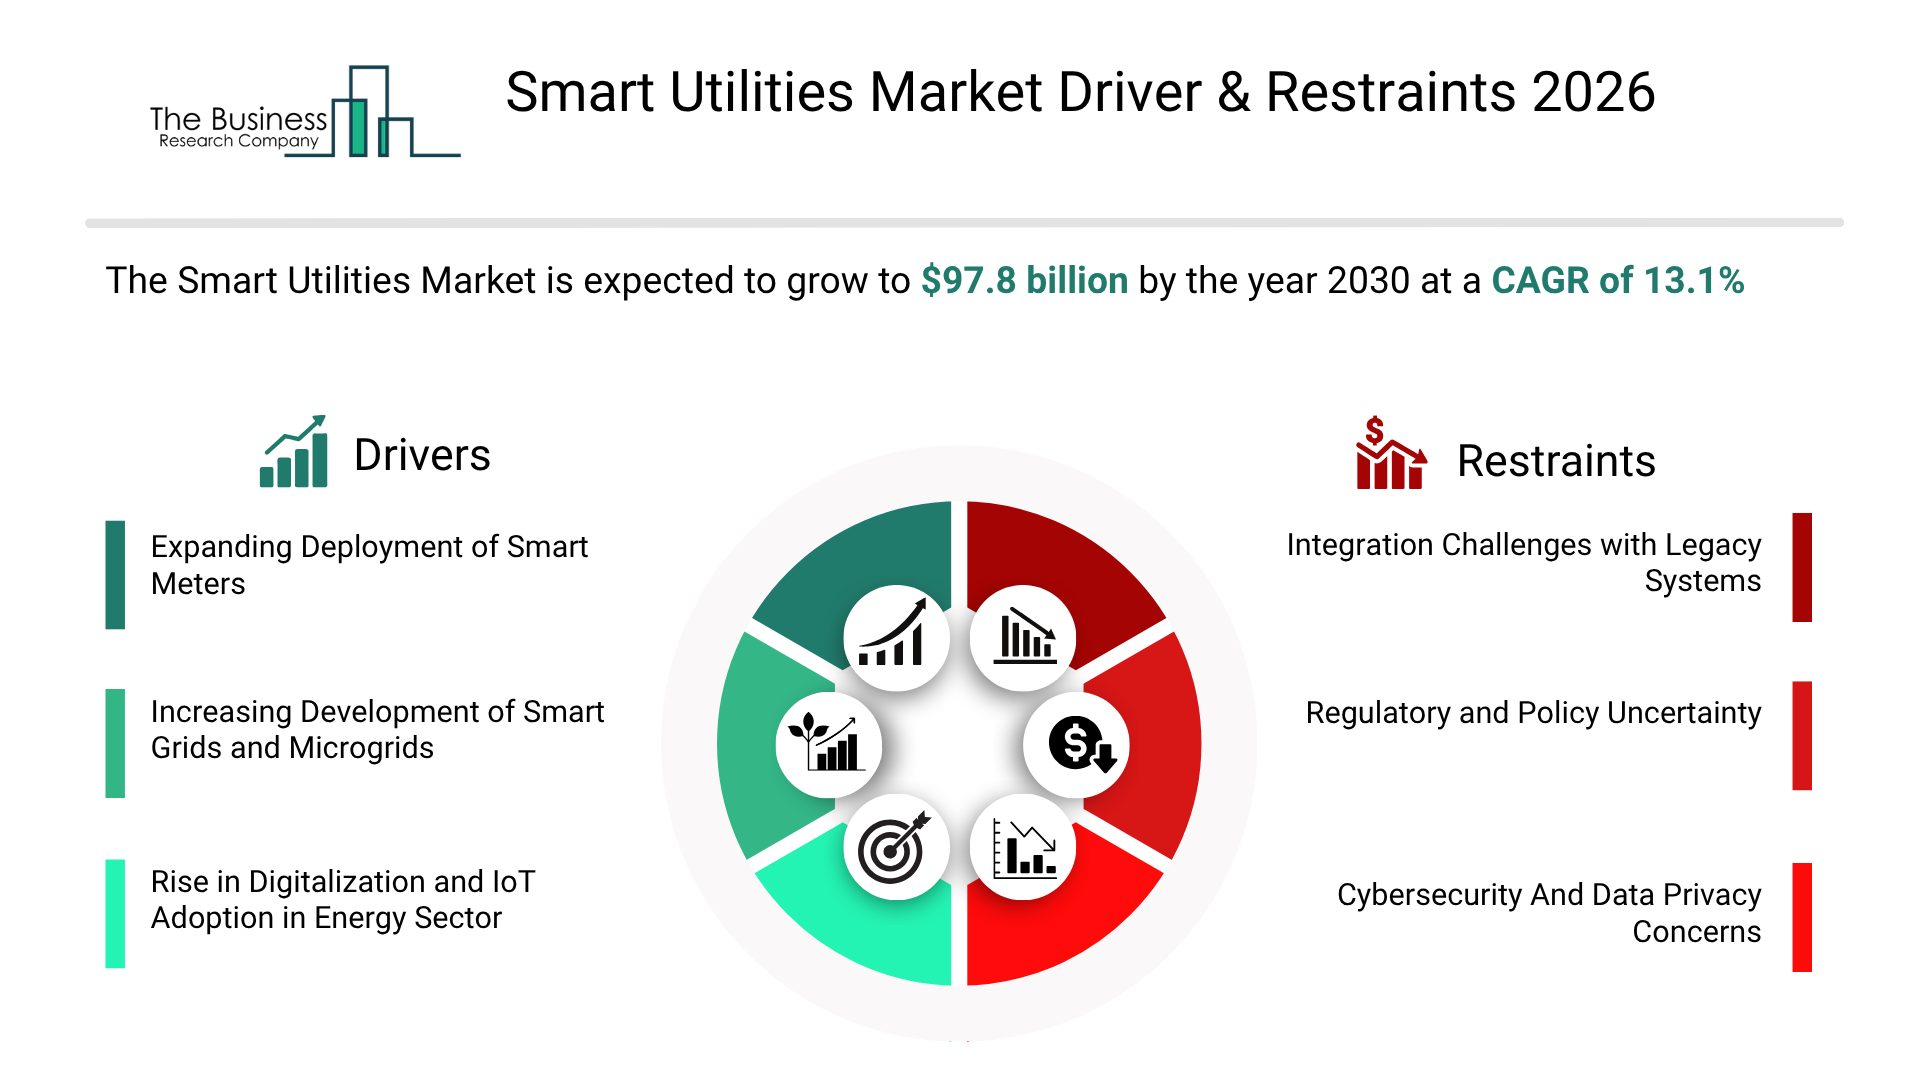
The smart utilities market is forecast to surpass $98 billion by 2030, capturing about 85% of the broader IoT in Utilities market, which itself is expected to reach approximately $114 billion by the same year. Within the massive Information Technology industry projected at nearly $13.8 trillion in 2030, smart utilities will represent close to 0.7% of the total market value. The sector is anticipated to expand at a compound annual growth rate of 13% through 2030.
Request A Free Sample Of The Smart Utilities Market Report
https://thebusinessresearchcompany.com/sample_request?id=16194&type=smp&name=Smart%20Utilities%20Market%20Report%202026&utm_source=EINPresswire&utm_medium=Paid&utm_campaign=Oct_PR
North America’s Dominance in the Smart Utilities Market Growth
By 2030, North America will lead the smart utilities sector with a market value of $32 billion, rising from $19 billion in 2025 and reflecting an 11% CAGR. This growth is driven by extensive smart grid modernization projects, increased integration of renewable energy sources into utility networks, and heavy investments in advanced metering infrastructure. IoT-enabled sensors allow for real-time grid monitoring, while a focus on energy efficiency and demand management is pushing utilities to upgrade digital platforms across the U.S. and Canada.
The United States stands out as the largest national market within North America, expected to reach $27 billion by 2030 from $16 billion in 2025, also growing at an 11% CAGR. The expansion is supported by accelerated deployments of smart meters and grid automation, alongside the integration of distributed energy resources such as rooftop solar panels and battery storage. Investments in cybersecurity, grid resilience, predictive analytics, AI-driven load forecasting, and enhanced customer-facing digital energy management tools all contribute to this upward trajectory.
Access The Detailed Smart Utilities Market Report Here
https://thebusinessresearchcompany.com/report/smart-utilities-global-market-report?utm_source=EINPresswire&utm_medium=Paid&utm_campaign=Oct_PR
Software Segment Leads the Smart Utilities Market Components
The smart utilities market is segmented into hardware, software, and services, with software projected to be the largest segment by 2030. Accounting for 52% of the market, software will be valued at $51 billion. This growth is fueled by AI-powered grid optimization and autonomous control systems, digital twin platforms used for network simulation and planning, cloud-native applications that provide real-time visibility, and predictive maintenance and outage management software. Additionally, interoperability frameworks enabling data exchange between utilities and continuous enhancements of enterprise analytics platforms worldwide will support software’s dominant role.
Market Segmentation by Technology and Application
Smart utilities technology divides primarily into wired and wireless systems. Application areas include meter hardware, communications and networking, power quality equipment, and various technologies essential for modern utility operations. These segments collectively underpin improvements in grid efficiency, reliability, and integration of renewable energy resources.
Primary Growth Drivers of the Smart Utilities Market
The global smart utilities market’s expansion hinges on three main factors. First is the rapid rollout of smart meters, which enable real-time energy monitoring, dynamic pricing, and demand response capabilities. As the backbone of smart utilities, smart meters generate substantial data streams, enhancing operational efficiency and customer engagement. This driver alone contributes roughly 1.7% annual growth to the market.
Secondly, the increasing investment in smart grids and microgrids plays a vital role. These systems enhance grid resilience, reduce transmission losses, and facilitate better integration of renewable energy sources. With rising occurrences of power outages and a stronger focus on local energy reliability, smart grids are becoming essential, contributing an estimated 1.5% yearly market growth.
Thirdly, growing digitalization and IoT adoption across the energy sector foster predictive maintenance, real-time monitoring, and data-driven decision-making. Although this driver ranks third due to its dependence on advanced digital infrastructure, it still adds about 1.0% annual growth to the market’s expansion.
Emerging Trends in Smart Utilities Focusing on Water Meter Upgrades
Advanced metering infrastructure (AMI) solutions are transforming water management by enabling real-time data collection and improved monitoring. For instance, in June 2024, ST Engineering introduced BrightCity, an AMI platform that converts traditional water meters into smart devices using a Meter Interface Unit. Features like wireless data transmission, integration with central Meter Data Management Systems, predictive leak detection, and customer usage portals help enhance efficiency, infrastructure oversight, and sustainable water management.
Leading Companies Driving Smart Utilities Innovation and Market Share
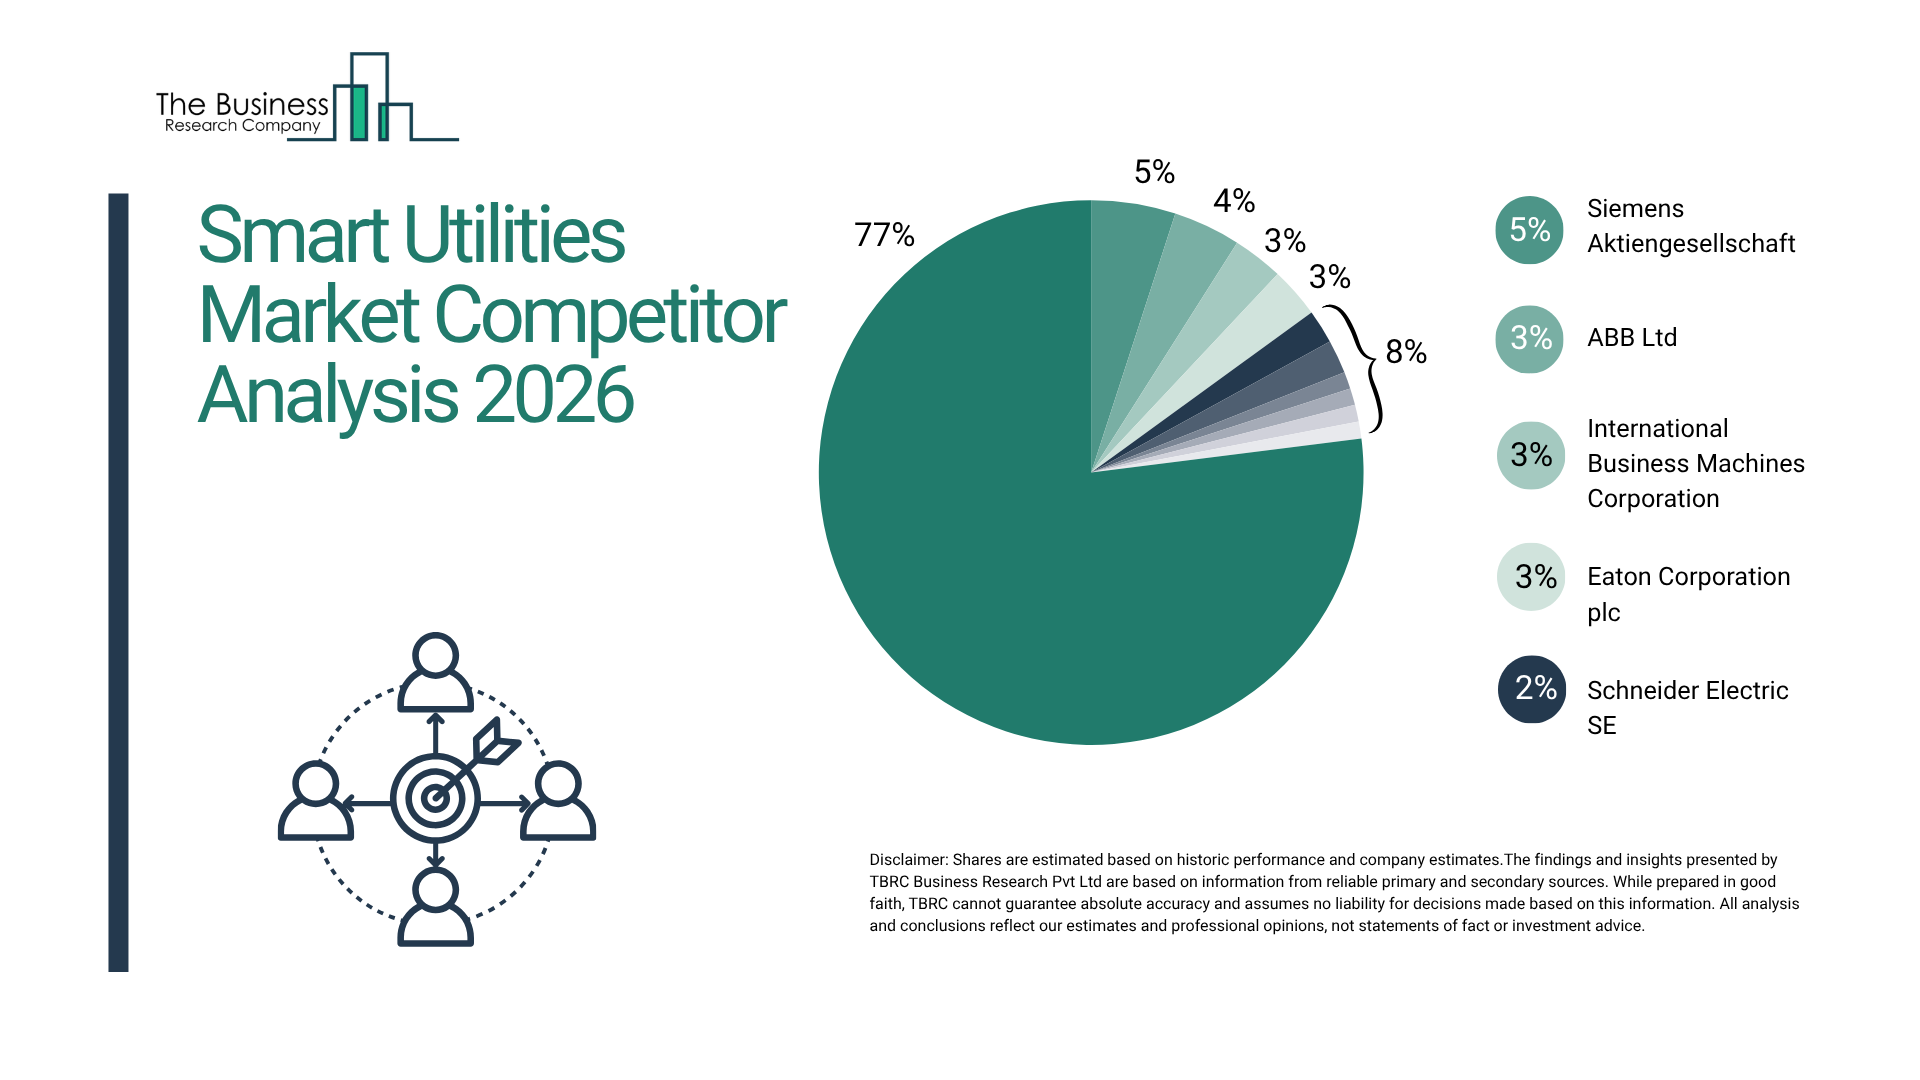
Siemens Aktiengesellschaft is the top player in the smart utilities market, holding a 5% share based on 2025 global sales. Its smart infrastructure and grid solutions division offers a wide range of products including smart grid technology, advanced metering infrastructure, energy management systems, grid automation tools, and digital utility platforms designed to improve distribution efficiency, renewable energy integration, and real-time monitoring capabilities.
Other key companies competing strongly in this space include ABB Ltd, International Business Machines Corporation (IBM), Eaton Corporation plc, Schneider Electric SE, GE Vernova, Tech Mahindra Limited, SAP SE, Oracle Corporation, Honeywell International Inc., Cisco Systems, Wipro Limited, Atos SE, Mitsubishi Electric Corporation, Hubbell Incorporated, Kamstrup A/S, S&C Electric Company, Landis+Gyr Group AG, Itron, Enel X S.r.l., Trilliant Holdings Inc., and Tantalus Systems Inc.
Market Concentration and Competitive Dynamics Among Top Vendors
The smart utilities market displays moderate fragmentation, with the top 10 companies generating 23% of total revenue in 2025. This distribution reflects technological and regulatory hurdles, such as stringent energy policies, complex grid integration challenges, cybersecurity demands, interoperability issues, and the need for consistently reliable real-time operations. Leading firms maintain their market positions through broad portfolios of smart grid solutions, digital utility platforms, energy management and automation offerings, and analytics, supported by solid utility partnerships and global distribution networks. As demand for real-time monitoring, grid modernization, renewable integration, and secure operations grows, innovation, collaboration, and geographic expansion will be crucial to sustaining their leadership.
The top players and their market shares in 2025 include Siemens Aktiengesellschaft (5%), ABB Ltd (4%), IBM (3%), Eaton Corporation (3%), Schneider Electric SE (2%), GE Vernova (2%), Tech Mahindra Limited (1%), SAP SE (1%), Oracle Corporation (1%), and Honeywell International Inc. (1%).
Strategies Companies Employ to Lead the Smart Utilities Market
Industry leaders focus on advancing smart grid technologies to enhance energy distribution stability and efficiency. They invest heavily in advanced metering infrastructure to improve data accuracy and utility operational efficiency. Expanding IoT networks for utilities strengthens real-time monitoring and grid reliability. Moreover, integrating AI-driven analytics enhances forecasting capabilities and overall energy management.
Forecasting Market Opportunities in Hardware, Software, and Services
The combined growth potential of hardware, software, and services in the smart utilities market is substantial, with a projected increase of over $44 billion by 2030. Between 2025 and 2030, hardware is expected to grow by $7 billion, software by $23 billion, and services by $14 billion. This growth is propelled by rapid deployment of advanced smart meters and grid edge devices, cloud-based platforms orchestrating utility operations, increased demand for integrated consulting and managed services, real-time analytics, and ongoing upgrades to operational technology infrastructure for power and water utilities. These trends highlight a strong focus on grid efficiency, data-driven energy management, and expansive digital transformation efforts.
Smart Utilities Market Supply Chain and Key Industry Players
The smart utilities supply chain is supported by a diverse set of raw material suppliers, wholesalers, distributors, and end-users. Major raw material suppliers include Siemens AG, Schneider Electric SE, ABB Ltd., General Electric Company, Honeywell International Inc., Hitachi Energy Ltd., Mitsubishi Electric Corporation, Toshiba Energy Systems and Solutions Corporation, Eaton Corporation plc, Emerson Electric Co., Cisco Systems Inc., Huawei Technologies Co. Ltd., Oracle Corporation, SAP SE, IBM, Microsoft Corporation, Intel Corporation, Qualcomm Incorporated, STMicroelectronics N.V., NXP Semiconductors N.V., Infineon Technologies AG, Texas Instruments Incorporated, Itron Inc., Landis+Gyr Group AG, and Sensus USA Inc.
Wholesalers and distributors such as WESCO International Inc., Graybar Electric Company Inc., Rexel S.A., Sonepar Group, Tech Data Corporation, Ingram Micro Inc., Avnet Inc., Arrow Electronics Inc., RS Group plc, Future Electronics Inc., ScanSource Inc., Allied Electronics and Automation, Anixter International Inc., Redington Limited, ALSO Holding AG, Esprinet S.p.A., Exclusive Networks SA, Westcon Group, D&H Distributing Company, Bechtle AG, Insight Enterprises Inc., CDW Corporation, Mindware FZ LLC, Logicom Public Limited, and EET Group A/S play a crucial role in market distribution.
Key end users include Enel Group S.p.A., Duke Energy Corporation, National Grid plc, Southern Company, E.ON SE, ENGIE SA, Tokyo Electric Power Company Holdings Inc., State Grid Corporation of China, Pacific Gas and Electric Company, American Electric Power Company Inc., Iberdrola S.A., EDF Energy, Suez SA, Veolia Environnement S.A., Thames Water Utilities Limited, Sydney Water Corporation, Saudi Electricity Company, Dubai Electricity and Water Authority, Singapore Power Limited, Fortis Inc., Tata Power Company Limited, NTPC Limited, Bharat Heavy Electricals Limited, Adani Transmission Limited, and NextEra Energy Inc.
What’s new in our 2026 market reports:
• Market attractiveness scoring and analysis
• Total addressable market (TAM) analysis
• Company scoring matrix graphics and tables
• Excel dashboards
• Market hotspots infographics
• Key technologies and future trends
• Updated graphics and tables
Learn More About The Business Research Company
The Business Research Company (www.thebusinessresearchcompany.com) is a leading market intelligence firm renowned for its expertise in company, market, and consumer research. We have published over 30,000+ reports across 27 industries and 60+ geographies. Our research is powered by 1,500,000 datasets, extensive secondary research, and exclusive insights from interviews with industry leaders.
We provide continuous and custom research services, offering a range of specialized packages tailored to your needs, including Market Entry Research Package, Competitor Tracking Package, Supplier & Distributor Package and much more.
Disclaimer: Please note that the findings, conclusions and recommendations that TBRC Business Research Pvt Ltd delivers are based on information gathered in good faith from both primary and secondary sources, whose accuracy we are not always in a position to guarantee. As such TBRC Business Research Pvt Ltd can accept no liability whatever for actions taken based on any information that may subsequently prove to be incorrect. Analysis and findings included in TBRC reports and presentations are our estimates, opinions and are not intended as statements of fact or investment guidance.
Contact Us:
The Business Research Company
Americas +1 310-496-7795
Europe +44 7882 955267
Asia & Others +44 7882 955267 & +91 8897263534
Email: marketing@tbrc.info
Follow Us On:
LinkedIn: https://in.linkedin.com/company/the-business-research-company
Oliver Guirdham
The Business Research Company
+44 7882 955267
Visit us on social media:
LinkedIn
Facebook
X
Legal Disclaimer:
EIN Presswire provides this news content "as is" without warranty of any kind. We do not accept any responsibility or liability for the accuracy, content, images, videos, licenses, completeness, legality, or reliability of the information contained in this article. If you have any complaints or copyright issues related to this article, kindly contact the author above.
